
CFDs and Spread Bets are complex instruments and come with a high risk of losing money rapidly due to leverage. 72.65% of retail investor accounts lose money when trading CFDs and Spread Bets with this provider. You should consider whether you understand how CFDs and Spread Bets work and whether you can afford to take the high risk of losing your money.

 Login


SEARCH
-
Search query too short. Please enter a full word or phrase.
-

Keywords
Popular Search


SEARCH
-
Search query too short. Please enter a full word or phrase.
-
Keywords
Popular Search


More record highs in stocks, dollar softer
Jamie Dutta >
4 December 2024 | Market Analysis | 5 min read
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
* South Korea won cuts losses after Parliament votes to lift martial law
* S&P 500 and Nasdaq again post all-time highs as US job openings rise
* Dollar eases on Fed rate cut expectations ahead of Friday’s NFP
* Gold marginally higher as USD falls and Treasury yields tick up
FX: USD had a relatively quiet, narrow range session printing an inside day. The jobs vacancies JOLTS data confirmed expectations about a rebound in the labour market. Of course, this comes ahead of Friday’s monthly NFP report. Money markets currently see a 74% chance of a 25bps Fed rate cut in a few weeks time, and a 26% likelihood of a pause. Dovish comments from the Fed’s Waller also helped bets on a December move.
EUR steadied, with prices also between yesterday’s high and low. The long-term support level at 1.0448 remains intact. Market concerns about the impending French government no confidence vote, likely Wednesday, appear to have eased.
GBP again saw similar price action to the euro. The 21-day SMA at 1.2718 has capped recent upside. Sterling is marking time like its peers in narrow range trading.
USD/JPY printed a doji with the yen very marginally outperforming on the day. A major Fib level (38.2%) of the July to September move resides at 148.12.
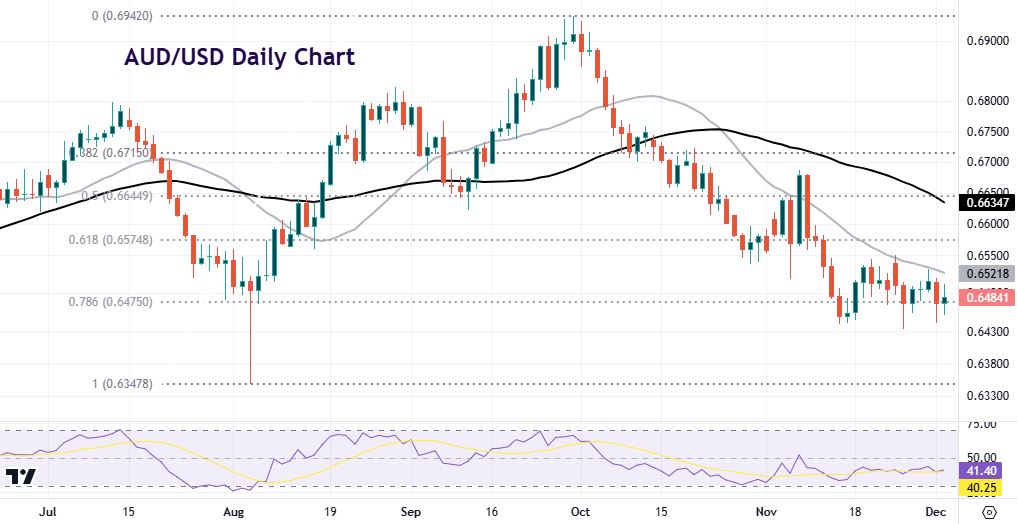
AUD sits on a minor Fib level at 0.6475. Traders are awaiting the GDP data. USD/CAD moved higher towards 1.41. Rate differentials and tariff threat uncertainty are trumping (pardon the pun) higher oil and solid risk sentiment.
US stocks: US stocks were mixed though the benchmark S&P 500 and the Nasdaq printed fresh all-tine highs. The S&P500 closed up 0.05% at 6,049. The tech-laden Nasdaq settled 0.31% higher at 21,229. The Dow lagged again finishing at 44,705, off 0.17%. Utilities were the weakest sector and communication services the top performing sector. Meta led the gainers, up over 3.5%. Tesla sold off 1.5% as its China sales fell by 4.3% in November as BYD sales surged. Chipmakers came under some pressure after a rare coordinated response from China’s top industry associations. They said Chinese companies should be wary of buying US chips.
Asian stocks: Futures are mixed. Asian equities were generally in the green after more record highs Stateside. The ASX 200 hit an all-time top driven by tech and healthcare. The Nikkei 225 outperformed and moved above 39,000 on tech. China stocks traded indecisively after a new package of chip export controls were unveiled by US.
Gold printed an inside day. That means its high and low were both inside the previous day’s range. A breakout will come soon, and it is likely to be explosive the longer this narrow range trading goes on. The 21-day SMA is at $2669.
Day Ahead – Australia GDP, US ISM Services
GDP growth in Australia has slowed, though the economy has avoided an outright contraction with 11 consecutive quarters of growth. That reflects a combination of strong population growth and government spending, plus the RBA having delivered less tightening than other major central banks. In Q3, public spending is expected to remain strong, while household consumption is likely to pick up, due to the government cost-of-living relief and tax cuts.
The US ISM survey data is predicted to ease to 55.5 from 56.0 in October. The latter print was a more than a two-year high. Services activity remains firmly in expansionary territory while employment strengthened. The prices paid component will be watched to see if there is a further moderation of inflation seen in the services economy. The employment side will also give a pointer to Friday’s NFP report.
Chart of the Day – AUD base building or bearish consolidation?
AUD/USD has been tracking sideways for the past few weeks. Support has been found on a minor Fib retracement level (78.6%) of the early August to late September move at 0.6475. The longer this trades in a narrow range, the bigger the range expansion and break out will be. That typically is in line with the dominant trend.
That means this is bearish consolidation before a breakdown through initial support around 0.6440 towards the August spike low at 0.6347. Alternatively, if US data especially starts to roll over, then a base around 0.6475 is in play. A move above the 21-day SMA at 0.6521 and the recent high at 0.6549 is needed to reverse the medium-term downtrend.
Key Points In This Article

Latest Financial Market Analysis


Market Analysis Tags
- # USD News
- # USDCAD News
- # USDJPY News
- # USDX News
- # Forex News
- # Forex News Today
- # GBPUSD News
- # EURUSD News
- # Currency Trading News
- # AUDUSD news
Related Articles
- Gold Price Falls 2% as Yields Drop: What It Means for XAUUSD Traders
- Why Euro Dollar Held Steady as French Yields Topped 5% – EURUSD Analysis
- Why Crude Oil Prices Rose as Iran Strike Reports Lifted Brent: UKOUSD and USOUSD Analysis
- Why Silver Fell as Oil Lifted Fed Hike Bets – XAGUSD Analysis
- Micron Stock Steadies After China-Led Memory Slide: What It Means for MU Traders
- Bank of Canada Interest Rate Announcement: 2.25% vs 3.1% CPI
- Why Texas Instruments Stock Edged Higher as Q4 Guidance Beat Estimates – TXN Analysis
- Why Meta Stock Rose After Hours as Q3 Revenue Beat and Class C Split Plan Landed – META Analysis