
CFDs and Spread Bets are complex instruments and come with a high risk of losing money rapidly due to leverage. 72.65% of retail investor accounts lose money when trading CFDs and Spread Bets with this provider. You should consider whether you understand how CFDs and Spread Bets work and whether you can afford to take the high risk of losing your money.

 Login


SEARCH
-
Search query too short. Please enter a full word or phrase.
-

Keywords
Popular Search


SEARCH
-
Search query too short. Please enter a full word or phrase.
-
Keywords
Popular Search


Middle East geopolitical tensions see USD bid
Jamie Dutta >
26 September 2024 | Daily Analysis | 5 min read
Jamie Dutta >
Jamie Dutta is a Market Analyst for Vantage. He comes with extensive experience as a full-time trader and financial market commentator, having worked as a trader in top tier investment banks and trading houses.
* Israel prepares for possible ground offensive in Lebanon
* Consumer rebound could delay BoE rate cuts, warns policymaker
* Swiss central bankers poised for year’s third rate cut
* Gold consolidates after smashing record on rate cut momentum
FX: USD traded back up through major long-term support at 100.61. Haven appeal on escalations in Israel and Lebanon were the main driver. There was little Fedspeak ahead of Chair Powell and NY Fed’s Williams set to appear later today.
EUR pushed up to a high at 1.1214 before closing near its lows on the day at 1.1132. That fresh year-to-date top level had not been seen since July 2023. The China stimulus measures had initially boosted the single currency which is a heavy exporter to the country. The 21-day SMA sits at 1.1093.
GBP posted another new cycle high at 1.3429 before paring gains and settling close to 1.33. The BoE’s Greene had earlier underlined the cautious stance being taken by the MPC relative to some of its peers within the G10 space.
USD/JPY pushed higher to major resistance at the long-term retracement level (50% of the 2023 low to 2024 high) at 144.58. That was its highest level since the start of September. Japan CPI is released on Friday.
AUD was the underperformer after printing a fresh cycle peak at 0.6908. We highlighted a long-term top at 0.6899. The major declined as headline inflation fell within the Reserve Bank of Australia’s (RBA) target range for the first time since October 2021. Core CPI hit its lowest since early 2022. USD/CAD bounced off the August lows around 1.3436 as risk sentiment turned. Notably, oil didn’t get a boost from Middle East tensions with Libyan supply worries weighing.
US Stocks closed mixed with mainly a negative bias. The S&P 500 lost 0.19% to settle at 5,722. The tech-laden Nasdaq 100 added 0.14% to finish at 19,972. The Dow closed 0.70% lower at 41,914. Energy saw the steepest drop among sectors, with only utilities and tech closing higher. Nvidia outperformed amid the megacaps while Meta posted modest gains after its Meta Connect Day saw several AI updates.
Asian stocks: Futures are mixed. Asian stocks were mostly in the green as China’s stimulus package continued to reverberate through markets. The ASX 200 was rangebound with weakness in tech and financials offset by strength in materials and mining. The Nikkei 225 traded around the 38,000 level with little news flow to shake investors. The Shanghai Composite and Hang Seng both rallied again with the PBoC’s rate cut being flagged by Tuesday’s briefing.
Gold traded marginally lower after printing another record at $2670. Treasury yields and the dollar were bid, trumping the uncertain geopolitical landscape and breaking a four-day win streak.
Day Ahead – SNB Meeting surprise?
We don’t cover the Swiss National Bank too much, but could it spring a surprise and follow the size of the FOMC rate cut? It is likely to continue its easing cycle with another 25bps cut for the third straight time, which will take the policy rate to 1%. But there is the potential for a larger cut of 50bps, with around 45% odds. Ongoing easing in inflation was seen in August’s CPI print at 1.1%. That was below the 1.2% estimate and well below the SNB’s overall Q3 forecast of 1.5%. This ongoing moderation should give the SNB more confidence on easing and see downward tweaks to its inflation forecasts.
We note the impact of currency strength on domestic industry was acknowledged by Chairman Jordan in a speech towards the end of August. Policymakers will be unhappy with the franc’s recent appreciation and could potentially shock with a bigger rate cut and stifle its ascent. As a reminder, this is the last policy meeting for Chairman Jordan who is to be replaced by current Vice-Chairman Schlegel.
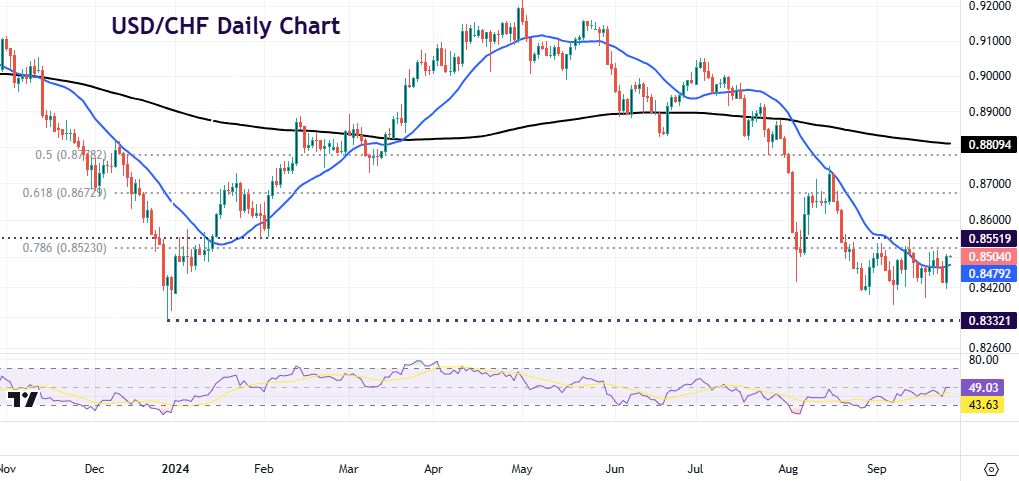
Chart of the Day – USD/CHF near lows
The CHF major could sell off if the SNB pull the trigger on a bigger half-point rate reduction. That would see the major rise. Perhaps the only other way the SNB can verbally turn the pair otherwise is by suggesting that there is no floor for the SNB policy rate – and by implication that rates could go negative again. But that is unlikely with strong chatter about an ‘overvalued’ swissie favoured.
Key long-term support sits at the late December low at 0.8322. Below here is the flash crash low from 2015 at 0.83. Intial resitance above comes at a minor Fib level of this year’s move higher at 0.8523, and then the July low from last year at 0.8551.
Key Points In This Article

Latest Financial Market Analysis


Market Analysis Tags
- # USD News
- # USDCAD News
- # USDJPY News
- # USDX News
- # Forex News
- # Forex News Today
- # GBPUSD News
- # EURUSD News
- # Currency Trading News
- # AUDUSD news
Related Articles
- Gold Price Falls 2% as Yields Drop: What It Means for XAUUSD Traders
- Why Euro Dollar Held Steady as French Yields Topped 5% – EURUSD Analysis
- Why Crude Oil Prices Rose as Iran Strike Reports Lifted Brent: UKOUSD and USOUSD Analysis
- Why Silver Fell as Oil Lifted Fed Hike Bets – XAGUSD Analysis
- Micron Stock Steadies After China-Led Memory Slide: What It Means for MU Traders
- Bank of Canada Interest Rate Announcement: 2.25% vs 3.1% CPI
- Why Texas Instruments Stock Edged Higher as Q4 Guidance Beat Estimates – TXN Analysis
- Why Meta Stock Rose After Hours as Q3 Revenue Beat and Class C Split Plan Landed – META Analysis